Ahead of the Curve: How US Manufacturers Are Restructuring Supply Chains Before New Tariffs Take Hold
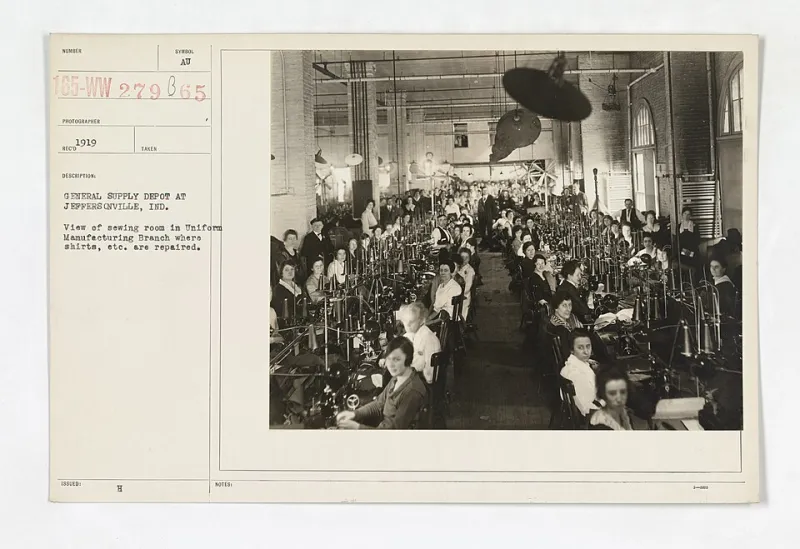
Photo: Unknown authorUnknown author or not provided, Public domain, via Wikimedia Commons
For most of the past decade, American mid-market manufacturers operated on a relatively stable set of assumptions about global trade. Input costs were predictable, sourcing relationships were entrenched, and tariff schedules—while occasionally disruptive—rarely demanded fundamental operational overhauls. That era is over.
With a new wave of trade policy changes anticipated to reshape import costs, country-of-origin requirements, and bilateral trade relationships, a meaningful segment of the US manufacturing base is no longer content to wait and respond. Instead, these companies are executing deliberate structural changes now—reorganizing supply chains, repositioning production, and renegotiating sourcing agreements—before new policies formalize and options narrow.
The firms that are moving earliest are learning something important: the cost of early action is almost always lower than the cost of reactive scrambling.
The Window Is Narrower Than Most Executives Realize
One of the most consistent observations among supply chain advisors working with mid-market clients is that executives routinely underestimate how long structural pivots actually take. Qualifying a new supplier in Vietnam or Mexico is not a six-week project. Establishing a contract manufacturing relationship in a new geography, navigating local regulatory requirements, auditing for compliance, and integrating the new partner into existing logistics networks can easily consume twelve to eighteen months—sometimes longer.
For companies whose current supply chains run heavily through tariff-exposed geographies, that timeline creates a real problem. If new duties take effect within a policy window that offers little runway, firms that have not already begun the transition process will face a stark choice: absorb higher input costs immediately or execute a rushed pivot that introduces its own risks around quality, delivery reliability, and contractual exposure.
The companies that are faring best are those that began scenario planning eighteen to twenty-four months in advance—not because they had perfect foresight, but because they treated trade policy volatility as a structural business risk rather than an external variable they could ignore until it materialized.
Decision Frameworks: Speed Versus Cost Versus Control
For executives weighing a supply chain restructuring, the central tension is rarely about whether to act. It is about how to calibrate the trade-offs between moving quickly, managing transition costs, and maintaining the quality and control standards that protect their brand.
Companies approaching this systematically tend to organize their analysis around three questions. First, what percentage of their cost structure is exposed to the tariff-affected categories, and how directly does that exposure flow through to margin? Second, what is the realistic timeline to qualify and integrate alternative sources, and does that timeline fit within the anticipated policy window? Third, what is the cost differential between absorbing the tariff temporarily while a transition is underway versus executing an accelerated—and therefore more expensive—pivot?
A specialty industrial components firm in the Midwest, for example, ran exactly this analysis in early 2024. The company sourced roughly forty percent of its machined parts from a single supplier in a tariff-sensitive geography. After modeling three scenarios—absorb and wait, partial near-shoring to Mexico, and full qualification of a domestic alternative—the leadership team concluded that partial near-shoring offered the best balance of speed and cost. They began supplier qualification immediately and completed the transition within fourteen months, positioning themselves well ahead of the anticipated policy changes.
Not every company will reach the same conclusion. For some, the cost differential between domestic and offshore production is wide enough that absorbing a moderate tariff increase remains the rational choice. For others, the exposure is concentrated enough that a full restructuring is warranted despite the short-term costs. The critical point is that the analysis must be done deliberately and early—not triggered by a policy announcement that has already taken effect.
Near-Shoring as a Structural Strategy, Not a Tactical Reaction
One of the more significant trends emerging from the current trade environment is the accelerating interest in near-shoring—relocating production or sourcing to geographically proximate countries, particularly Mexico and select Central American markets, that offer cost advantages alongside favorable trade treatment under existing agreements.
For US manufacturers, Mexico in particular has moved from a secondary consideration to a primary strategic option. The combination of geographic proximity, established manufacturing infrastructure, a skilled labor base in key industrial sectors, and preferential treatment under the United States-Mexico-Canada Agreement makes it a compelling near-shoring destination for a wide range of product categories.
Companies that have executed near-shoring transitions thoughtfully report benefits that extend beyond tariff mitigation. Shorter transit times reduce working capital tied up in inventory. Greater geographic proximity improves visibility and responsiveness in the supply chain. And in categories where just-in-time production is a competitive requirement, the logistical advantages of near-shoring can translate directly into customer retention.
That said, near-shoring is not a frictionless solution. Capacity constraints in key Mexican industrial clusters have become a meaningful challenge as demand has accelerated. Lead times for establishing new facilities or securing contract manufacturing arrangements have lengthened, and real estate and labor costs in high-demand zones have risen. Companies entering the near-shoring market now are competing for a more constrained set of options than those who moved two or three years ago.
The Organizational Dimension: Restructuring Is Not Just a Supply Chain Problem
One aspect of tariff-driven restructuring that receives insufficient attention is the organizational complexity it introduces. Moving production or sourcing across geographies is not simply a logistics exercise—it requires legal entity restructuring in some cases, new compliance frameworks, changes to procurement team responsibilities, and in many instances, a reorientation of the relationships that senior leadership prioritizes.
Mid-market companies, in particular, often lack the internal bandwidth to manage a major supply chain transition while simultaneously running day-to-day operations. The firms that execute these pivots most effectively tend to be those that treat the restructuring as a dedicated initiative with assigned leadership, defined milestones, and board-level visibility—not a project handed to an already-stretched operations team as an additional responsibility.
External advisory support can play an important role here, particularly for companies navigating unfamiliar geographies or regulatory environments for the first time. The value of a partner with established relationships in the target market—whether that is a near-shoring destination in Latin America or an alternative sourcing geography in Southeast Asia—can compress timelines significantly and reduce the risk of costly missteps during supplier qualification.
The Strategic Imperative: Preparation as Competitive Advantage
The companies emerging strongest from the current trade policy environment share a common characteristic: they have internalized the idea that trade policy volatility is a permanent feature of the global business landscape, not a temporary disruption to be managed and forgotten.
For US mid-market manufacturers and exporters, that means building supply chains with deliberate redundancy and geographic diversification—not because every contingency will materialize, but because the cost of optionality is almost always lower than the cost of being caught without it.
The tariff landscape of the coming years will create genuine competitive differentiation between companies that have restructured proactively and those that have not. The window to act with sufficient runway is still open. For most companies, it will not remain open indefinitely.